
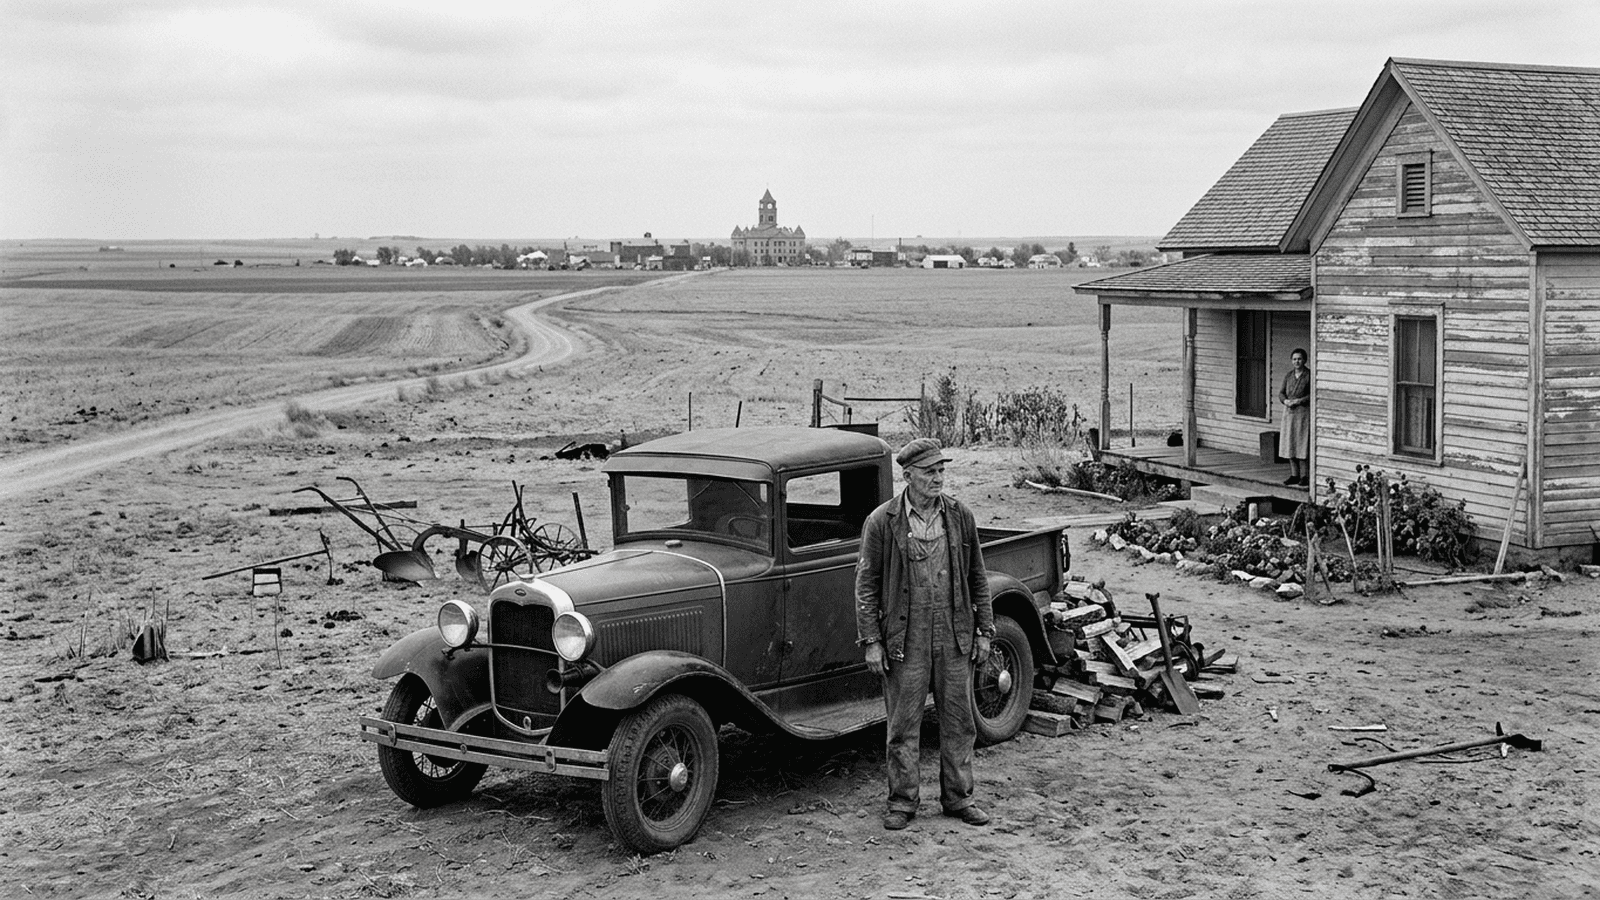
The 1934 Frazier-Lemke Act sought to protect indebted farmers, including many in the Great Plains, from foreclosure during the Depression. In 1935, the U.S. Supreme Court struck it down as an unconstitutional impairment of creditors’ property rights; Congress revised the law, and the Court upheld the new version in 1937.
TLDR: Congress tried to shield Depression-era farmers from foreclosure through the 1934 Frazier-Lemke Act. The Supreme Court invalidated the law in 1935, ruling that it stripped mortgage lenders of protected property rights. Congress revised the measure, and the Court upheld the new version in 1937.
In the depths of the Great Depression, farm foreclosures threatened families across the Great Plains. Falling crop prices and mounting debts had left many farmers unable to meet mortgage payments. Congress responded in 1934 with the Frazier-Lemke Farm Bankruptcy Act, a measure sponsored by Representative William Lemke of North Dakota. Its passage set up a constitutional confrontation over whether the federal government could give distressed farmers time and protection from creditors. Farm income had fallen sharply after the 1929 crash, while earlier borrowing left landowners exposed when payments came due; foreclosure could also disrupt local communities dependent on farm production.
The law amended federal bankruptcy rules to let a farmer seek relief in court and remain on a mortgaged farm while working toward repayment. A judge could delay foreclosure for up to five years and permit the farmer to buy back the property at an appraised value. The statute aimed to prevent the forced sale of farms during a collapse in agricultural prices. It did not erase every debt, but it substantially changed what mortgage lenders could do while a case proceeded.
Lenders challenged the measure after it affected a foreclosure brought by the Louisville Joint Stock Land Bank against Kentucky farmer George Radford. The dispute reached the Supreme Court as Louisville Joint Stock Land Bank v. Radford. On May 27, 1935, the justices ruled unanimously that the statute went too far. Chief Justice Charles Evans Hughes wrote that Congress had taken away important property rights belonging to mortgage holders, including their ability to obtain the value of their security through foreclosure.
The Court relied on the Fifth Amendment’s protection against the taking of private property without just compensation. Congress had broad authority to establish bankruptcy laws, the justices acknowledged, but that power did not permit the government to strip creditors of established rights without compensation. The ruling invalidated the law’s central protections. It arrived amid a wider national dispute over the limits of federal power, as the Roosevelt administration and Congress pursued ambitious responses to economic collapse.
For farmers facing foreclosure, the decision was immediate and consequential. The ruling did not end federal efforts to provide relief, but it left the original law unusable in its existing form. Supporters of the measure argued that emergency conditions demanded stronger protection for farm families; lenders and their allies insisted that relief could not simply transfer losses onto secured creditors. The case exposed how constitutional limits could shape—and sometimes halt—economic policy even when lawmakers acted in response to widespread distress. The ruling also underscored that bankruptcy relief could not nullify a secured claim.
Congress returned to the problem within months. In August 1935, it enacted a revised version of the farm bankruptcy law, changing the process and adding protections for creditors, including compensation for the use of mortgaged property during a stay. The new law still sought to help farmers reorganize and retain their land, but it was designed to address the defects identified by the Court. Lawmakers had not abandoned the policy goal; they had rewritten the means of pursuing it.
The revised statute faced another constitutional test in Wright v. Vinton Branch, decided in 1937. This time, the Supreme Court upheld the law, finding that its updated terms better protected creditors while allowing farmers a chance to reorganize. The sequence—from enactment to invalidation and revision—became a notable example of New Deal policy being reshaped through judicial review and congressional response. It also left a lasting lesson for federal lawmakers: emergency legislation could address economic hardship, but its details mattered when private property and constitutional protections were at stake.

Lila Hayes serves as a Staff Writer for Just Right News, where she anchors the “Courts, Law, and Constitutional Order” beat. Her work is defined by a steadfast commitment to the foundational principles of the American republic and a rigorous defense of the legal frameworks that ensure national stability. As a primary voice for the outlet, she provides readers with a clear-eyed analysis of the judiciary, focusing on the importance of originalism and the preservation of the separation of powers.
Lila’s perspective was forged in the American heartland. Raised in St. Louis, Missouri, she grew up in a Hispanic household where the values of hard work, faith, and respect for the law were paramount. Her upbringing instilled in her a deep appreciation for the American Dream and the legal protections that make it possible. This Missouri background remains a cornerstone of her reporting, providing a grounded, common-sense counter-narrative to the often-insular legal circles of the coastal elite. She understands that the decisions made in high-court chambers have real-world consequences for families and small business owners across the country.
At Just Right News, Lila has become widely recognized for her signature feature series, “The Rulebook of Power.” In this ongoing project, she delves into the mechanics of the federal government, examining how administrative overreach and judicial activism can threaten the delicate balance of the Constitution. She approaches her beat with the tenacity of a veteran journalist and the precision of a legal scholar, consistently advocating for a judiciary that interprets the law as written rather than legislating from the bench. For Lila, the Constitution is not a “living” document subject to the whims of modern social trends; it is a fixed standard that ensures the government remains the servant of the people, not their master.
Now based in Philadelphia, Pennsylvania, Lila finds herself at the very epicenter of American constitutional history. Living and working in the city where the Founders drafted the documents she defends daily provides a constant source of inspiration. The historic halls and landmarks of Philadelphia serve as a daily reminder of the high stakes involved in her reporting. Her presence in the city allows her to bridge the gap between the historical intent of the law and its contemporary application, ensuring that the legacy of the Founding Fathers remains central to the national conversation.
Throughout her career, Lila has remained dedicated to the idea that a free society requires an informed citizenry and a transparent legal system. Her reporting is more than just a collection of headlines; it is a defense of the constitutional order that has sustained the nation for over two centuries. By focusing on the “Rulebook of Power,” she ensures that her readers understand not just what is happening in the courtrooms, but why those decisions matter for the future of American liberty. Lila Hayes continues to be a vital voice for those who believe that the law should be a shield for the citizen and a constraint on the state.