
Nations and corporations face mounting fiscal pressure as France targets a €54 billion budget correction and UK businesses warn that soaring labor costs are stifling private investment.
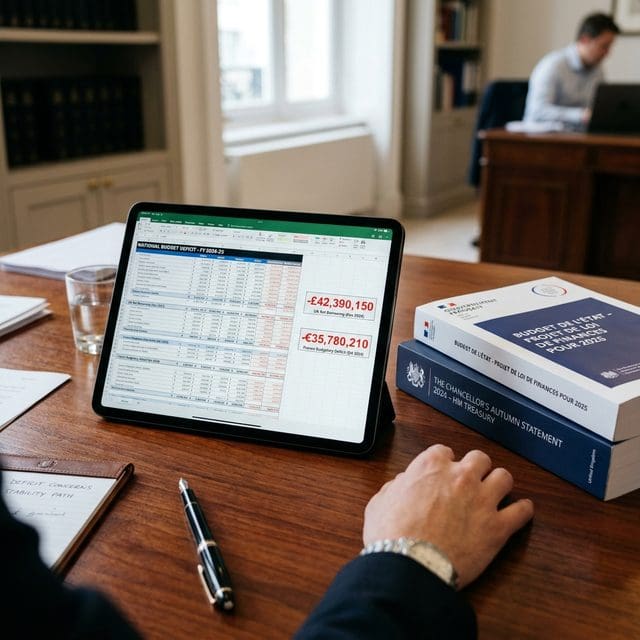
The fiscal reality of 2026 is catching up to Western economies as governments and corporations grapple with the consequences of ballooning debt. In France, the government unveiled its 2027 draft budget on October 1, signaling a pivot toward austerity. The plan targets a fiscal effort of €54 billion to bring the deficit down to 5% of GDP from 5.4% in 2026. Without these interventions, Prime Minister Sébastien Lecornu warned the deficit could reach 6.5%, a level that would likely trigger market instability.
The French ledger reveals a stark structural imbalance. Debt-interest costs are projected to rise by €12 billion, reaching €91 billion in 2027, as public debt climbs past 120% of GDP. To mitigate this, the government aims to slash the social-security deficit from €22 billion to approximately €12 billion. Proposed measures include €5.1 billion in health-sector savings and €5.5 billion extracted from retirees by weakening pension indexation for those earning above €1,260 monthly. These maneuvers demonstrate the difficult trade-offs required when state spending outpaces economic growth.
Across the English Channel, the United Kingdom faces similar scrutiny ahead of Chancellor John Healey’s October 28 Budget. Data-driven critiques of current spending patterns suggest a partisan tilt in welfare distribution. Analysis shows that £8.8 billion of a £12 billion increase in benefit spending has been concentrated in Labour-held seats. This 73% concentration of new welfare spending raises questions about the equitable distribution of federal funds and the sustainability of the social safety net as the government seeks further cuts to fund defense and social care.
The private sector provides a real-time audit of how these fiscal policies translate to the high street. JD Wetherspoon reported a 28% drop in pre-tax profits to £58.6 million for the fiscal year ending July 26, despite a 5.2% increase in revenue to £2.24 billion. The forensic breakdown of costs shows a £46 million increase in wages, £31 million in repairs, and £9 million in business rates. Consequently, the firm’s investment in existing sites plummeted from £62.5 million to £26.3 million, with total capital expenditure falling from £117 million to £74.2 million. Chairman Tim Martin attributed the decline to tax hikes, highlighting a disconnect between government revenue targets and corporate viability.
In the technology sector, the shift toward digital efficiency continues. Visa reported that business programs now represent 17% of stablecoin-linked card volume, with payment volume growing nearly 200% year-on-year. While companies like Micron report record revenues driven by AI demand—allowing for share buybacks rather than debt servicing—the broader economy remains tethered to the rising cost of traditional infrastructure. Micron’s data-center revenue grew 11-fold year-on-year, yet this private success stands in contrast to the fiscal strain felt by public institutions.
As the U.S. Congress reauthorized the ACT for ALS Act on September 28, the underlying theme remains clear: the cost of maintaining existing social commitments is rising faster than the tax base can support. Whether through French pension reforms or UK welfare audits, the data suggests the era of consequence-free deficit spending is meeting the hard reality of interest rates and administrative overhead. For the taxpayer, the ledger shows that without significant reform, the cost of governance will continue to crowd out the services it is intended to provide.
Max Grant serves as the Senior Correspondent for Data and Financial Forensics at Just Right News, where he brings a meticulous, investigative eye to the complex world of numbers. In an era where media narratives often overshadow objective reality, Max operates on a simple but firm principle: while rhetoric can be manipulated, the ledger never lies. As the architect behind the acclaimed feature series “Numbers That Talk,” he has carved out a vital niche in conservative journalism, translating dense financial data into clear, actionable insights for the American public.
Max’s journey to the forefront of financial reporting began in Buffalo, New York. Growing up in the Queen City, he was raised with the grit and grounded perspective typical of the Rust Belt. Buffalo is a place that understands the value of a dollar and the consequences of economic shifts on the working class. This upbringing instilled in Max a deep-seated respect for fiscal responsibility and a healthy skepticism toward bureaucratic overreach. He carries the spirit of his hometown into every investigation, viewing his work not just as reporting, but as a form of public service dedicated to protecting the interests of taxpayers and everyday citizens.
Now based in Brooklyn, New York, Max operates from the heart of one of the world’s most influential financial and cultural hubs. This vantage point allows him to keep a close watch on the institutions that drive the global economy. Living and working in a city often defined by progressive policy experiments, Max provides a necessary counter-perspective, using his forensic skills to analyze the real-world costs of local and national governance. His proximity to the financial district ensures he is never far from the source of the data he deconstructs, yet he remains firmly rooted in the conservative values that prioritize transparency and individual liberty.
His beat, Data and Financial Forensics, is more than just a job title; it is a commitment to uncovering the truth hidden within spreadsheets and annual reports. In “Numbers That Talk,” Max dives deep into federal spending, corporate accountability, and the intricate web of international finance. He has a unique ability to spot the anomalies that others miss, identifying where public funds are being mismanaged or where economic policies are failing to deliver on their promises. His reporting is characterized by a relentless pursuit of clarity, stripping away the jargon to show readers exactly how their money is being used and how the economy is truly performing.
At Just Right News, Max Grant is recognized as a steady hand and a sharp mind. He understands that for a free society to function, its citizens must have access to the facts regarding their financial future. By combining his British heritage’s tradition of rigorous inquiry with an American drive for accountability, Max ensures that the numbers don’t just sit on a page—they tell the story of where the country has been and where it is headed. His work stands as a testament to the power of forensic journalism in holding the powerful to account and championing the principles of a transparent, fiscally sound nation.