
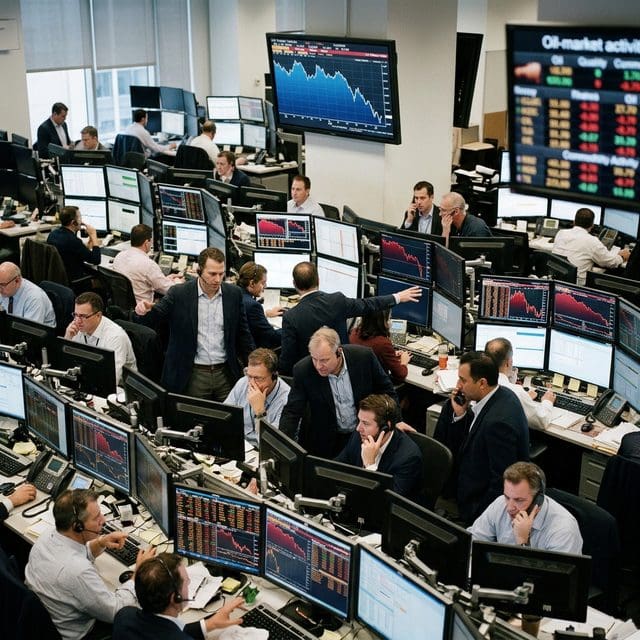
SPY fell 1.79% as technology shares led a broader retreat, Treasury yields eased and oil rose on fresh supply concerns.
U.S. stocks fell sharply, with SPY down 1.79% on the session and the S&P 500 losing 1.82%. The day’s damage was concentrated in technology: the Nasdaq Composite fell 2.86%, the Nasdaq 100 dropped 3.5%, and the MSCI World Index declined 1.5%. The S&P 500 also slipped below its 100-day moving average, while the Nasdaq 100 briefly entered correction territory, according to Bloomberg reporting via Swissinfo.
The central question for investors was whether the vast sums flowing into artificial intelligence infrastructure can earn an adequate return. Recent results and outlooks sharpened concerns about cash demands and the health of the businesses expected to fund the investment. Intel plunged 28.6%, its largest decline in more than four decades, after its fourth-quarter profit forecast fell well short of analyst expectations, according to The Associated Press. Reuters reported that indications of slowing PC demand added to pressure on the chipmaker and suggested weakness could persist through 2027.
Amazon also came under scrutiny after reporting substantial cash burn alongside heavy investment in AI infrastructure. Bloomberg’s reporting identified the broader concern: the core businesses of major U.S. technology companies are supporting roughly $750 billion in AI spending in 2026. If advertising, consumer or retail operations weaken, investors may question whether those companies can sustain spending—or when the investment will translate into profits. S&P Global Ratings also moved toward a possible downgrade of Meta within two years, citing elevated AI spending and balance-sheet pressure, according to Bloomberg via Swissinfo.
The move was more than a routine reaction to individual earnings reports. Reuters said the PHLX Semiconductor Index fell more than 7%, its largest daily decline since late June, and the S&P 500 technology index dropped 4.2%, its weakest session since early June. Apple reclaimed the title of the world’s most valuable company from Nvidia as investors sought relative safety in the iPhone maker, Bloomberg reported. That shift suggests investors were reassessing risk within technology, not abandoning the sector uniformly.
Government bonds gained as equities retreated. The 10-year Treasury yield fell 5.8 basis points to 4.931%, the 30-year yield declined 1.97 basis points to 5.3093%, and the two-year yield dropped 6.64 basis points to 4.59%, Reuters reported. Bond prices and yields move in opposite directions; the lower yields were consistent with investors seeking shelter, though the day’s data alone do not establish a lasting change in interest-rate expectations.
Oil moved in the opposite direction. U.S. crude settled at $104.12 a barrel, up 2.08%, while Brent reached $117.63, up 2.4%. Reuters linked the rise to a tanker attack in the Strait of Hormuz, which heightened concern about supply disruptions. That matters beyond energy investors: sustained increases in crude can feed into fuel and transportation costs. A MarketWatch report in the supplied material also warned that U.S. households heating with oil could pay $750 more this winter as heating-oil prices reach record highs.
The supplied reporting did not provide a reliable foreign-exchange move for the session, so the dollar’s direction cannot be established here. For working households, the day offered two practical signals: markets are demanding clearer evidence that AI spending will pay off, and higher oil prices could add pressure to household budgets if the supply concern persists. One volatile session does not settle either question, but the contrast between falling shares, lower Treasury yields and rising crude captures the competing risks investors were weighing.
Jordan Lee serves as the Senior Correspondent for Wall Street, Finance, and Monetary Systems at Just Right News. Based in the heart of the world’s financial capital, New York City, Lee brings a sharp, principled eye to the complex mechanisms that drive the global economy. His reporting is defined by a commitment to fiscal responsibility, the defense of the free market, and a deep-seated belief that a transparent monetary system is the bedrock of a free society.
Raised in Portland, Oregon, Lee’s perspective was forged in a city that has undergone significant cultural and economic shifts. His upbringing in the Pacific Northwest instilled in him a profound appreciation for the industriousness of small business owners and the importance of local economic stability. Watching the evolution of his hometown’s landscape sparked an early interest in how federal fiscal policy and large-scale financial trends eventually trickle down to the average citizen. This background provides him with a unique vantage point; he understands the growing disconnect between the policy-making elite and the reality of Main Street, a theme that frequently resonates throughout his work.
Now operating from his base in New York City, Lee bridges the gap between the high-stakes trading floors of Manhattan and the households of everyday Americans. He views the financial sector not merely as a collection of numbers and tickers, but as a vital engine of American prosperity that requires constant vigilance and accountability. His reporting often highlights the dangers of centralized financial control and the necessity of maintaining a system that rewards merit, risk-taking, and innovation.
As the creator and lead of the featured series, “The Invisible Economy,” Lee pulls back the curtain on the often-opaque world of monetary systems. He specializes in translating the dense jargon of central banking and international finance into actionable insights for the Just Right News audience. His work explores the “invisible” forces—such as inflationary pressures, regulatory creep, and the expansion of the administrative state—that erode the purchasing power of American families. By focusing on these systemic issues, Lee empowers readers to understand the hidden forces shaping their financial independence.
Lee’s journalistic philosophy is rooted in a steadfast commitment to traditional American values. As an Asian American professional who has navigated the competitive corridors of the financial world, he is a vocal advocate for meritocracy and the preservation of the American Dream. He believes that a stable currency and a predictable regulatory environment are essential for national sovereignty and individual liberty. His reporting frequently warns against the risks of government overreach in the private sector, arguing that the most effective solutions to economic challenges arise from competition and individual enterprise rather than bureaucratic mandates.
At Just Right News, Jordan Lee remains dedicated to providing a clear-eyed defense of the taxpayer. Whether he is analyzing market volatility or investigating the long-term implications of national debt, his mission is to provide the truth about where the money is going and what it means for the future of the country. Through his rigorous analysis and principled stance, Lee has become a trusted voice for those who value a strong, sovereign, and fiscally sound America.