

A possible Tesla–SpaceX combination faces questions about national-security safeguards, shareholder approval and the reach of corporate power, including from Texas’s incoming attorney general.
A possible merger between Tesla and SpaceX is drawing scrutiny in Texas, where Attorney General-elect Nathan Johnson says a transaction of that scale demands close examination. The talks remain unannounced, and reports describe unresolved questions over ownership, governance and operational separation—not a completed deal or a formal antitrust challenge.
In a Bloomberg interview reported November 13, Johnson said any merger of such consequence warrants “tremendous scrutiny.” He also warned that Elon Musk’s corporate empire could cross the line into using public power for private gain. According to Investing.com, Johnson plans to refocus the Texas attorney general’s office on antitrust litigation and consumer protection, moving away from outgoing Attorney General Ken Paxton’s culture-war initiatives. Johnson has not, in the cited reporting, announced a specific legal action against the companies.
That scrutiny matters even before regulators decide whether the transaction would violate competition law. Tesla sells electric vehicles and related products; SpaceX operates launch services and holds U.S. government and defense contracts. Combining businesses with reach across transportation, communications and national-security infrastructure could raise questions about control, conflicts of interest and access to public resources. The available reporting does not establish that the companies hold a monopoly in any defined market or that an antitrust agency has opened a review.
A central reported complication is the tension between Tesla’s China operations and SpaceX’s U.S. defense work. Reports say the parties are considering ways to ring-fence Tesla’s Chinese business from SpaceX’s government and defense contracts. The arrangement’s design and effectiveness remain unclear, but could become important to regulatory and shareholder approvals. The reporting does not describe a finalized separation or explain what oversight would ensure that any boundaries remain effective after a merger.
The issue is more than corporate paperwork. A combination placing sensitive government work and a major global business under common control would require scrutiny of decision-making, information protections and whether safeguards could be enforced. The source material does not detail a proposed ring-fencing plan or show whether it would adequately address those risks. A promise to separate operations, if made, would need to be assessed against actual control, information flows and accountability—not simply accepted as a label.
Shareholder approval is another hurdle. Tesla-related reporting says the transaction would require approval from 50% of all outstanding shares, rather than a majority of votes cast. A December announcement would likely require a separate special shareholder meeting. Bloomberg reports that boards and advisers are still negotiating ownership, governance and share-exchange terms, and discussions could extend into early 2027. No final terms or announcement are confirmed, making it impossible to assess the proposed exchange or how the companies’ owners would share control.
Political scrutiny could grow, too. Reports say Democrats’ control of Congress after the midterm elections could bring investigations into Musk’s business and political activities. Congressional attention would not determine whether a merger is lawful, but could intensify demands for information about the arrangement and its public-contract implications. The reports do not identify a specific investigation already under way.
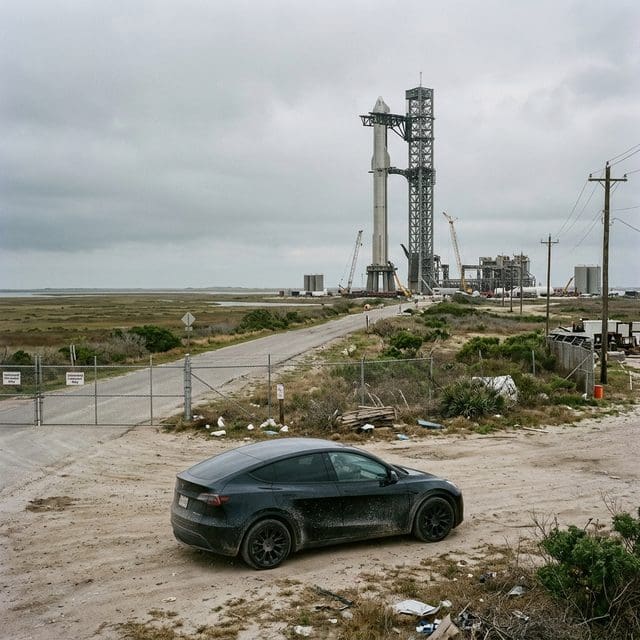
The discussions coincide with a planned SpaceX Starship flight. Reuters reported that SpaceX aimed to recover both the Super Heavy booster and Starship’s upper stage in a first “double catch,” with upper-stage recovery expected about 22 hours after launch and a possible catch around 2:45 p.m. CT Saturday. The flight was still pending FAA authorization on November 13. The launch and merger questions are separate, but both involve private companies operating in areas subject to public oversight.
For consumers and smaller competitors, the key question is whether a merger would give one corporate group advantages rivals cannot match or reduce meaningful choices. The reports do not establish those effects, and no terms have been published to assess them. Nor do they identify an FTC or Justice Department case. That uncertainty calls for careful scrutiny, not an assumption of either wrongdoing or harmlessness. If talks advance, regulators and shareholders will need evidence about the deal’s structure, competitive effects and safeguards for government work.
Greg Sanders serves as the Senior Correspondent for Corporate Power and Antitrust at Just Right News, where he brings a principled, conservative perspective to the complex intersection of big business, government regulation, and the American consumer. With a career dedicated to investigative depth and economic clarity, Greg has become a leading voice in examining how the consolidation of industry power impacts the foundational values of the free market and individual liberty.
Raised in Denver, Colorado, Greg’s reporting is deeply informed by the Western spirit of independence and a healthy skepticism of centralized authority. Growing up in the shadows of the Rockies, he witnessed firsthand the importance of local entrepreneurship and the vital role that small-medium enterprises play in sustaining vibrant communities. This upbringing instilled in him a belief that the American Dream is best preserved when the playing field remains level and when competition—rather than backroom deals between corporate lobbyists and federal regulators—dictates success. For Greg, the rugged individualism of his home state serves as a constant reminder that the economy should serve the people, not the other way around.
Now based in Chicago, Illinois, Greg operates from the heart of the nation’s industrial and financial crossroads. His location in the Midwest provides him with a unique vantage point to observe the real-world consequences of corporate overreach. From the boardrooms of the Loop to the manufacturing hubs that define the region, he tracks the movement of capital and the shifting tides of market influence. Chicago’s history as a center of trade and labor offers a rich backdrop for his work, allowing him to bridge the gap between high-level economic theory and the lived experiences of hardworking Americans who feel the squeeze of monopolistic practices.
At Just Right News, Greg’s beat focuses on the “new monopolies” and the rise of “woke” corporate culture. He argues that when corporations become too large, they often abandon their fiduciary duties to shareholders in favor of social engineering and political posturing. His reporting seeks to hold these “Titans” accountable, ensuring that the power of the purse is not used to silence dissent or bypass the democratic process. He is a firm advocate for the idea that true conservatism requires a vigilant defense of competition, preventing any single entity—public or private—from exerting undue control over the lives of citizens.
This mission is most clearly seen in his acclaimed feature series, “The Titans and the Toll.” In this ongoing project, Greg explores the human cost of market consolidation, from the erosion of consumer choice to the decline of local economies. Through rigorous analysis and boots-on-the-ground reporting, he documents how the concentration of power in sectors like tech, agriculture, and finance creates a “toll” paid by the average family.
Greg Sanders remains committed to the idea that a transparent, competitive market is the greatest engine for prosperity ever devised. Through his work at Just Right News, he continues to provide the essential oversight necessary to protect that engine from the encroaching influence of corporate giants and the bureaucratic structures that enable them.