

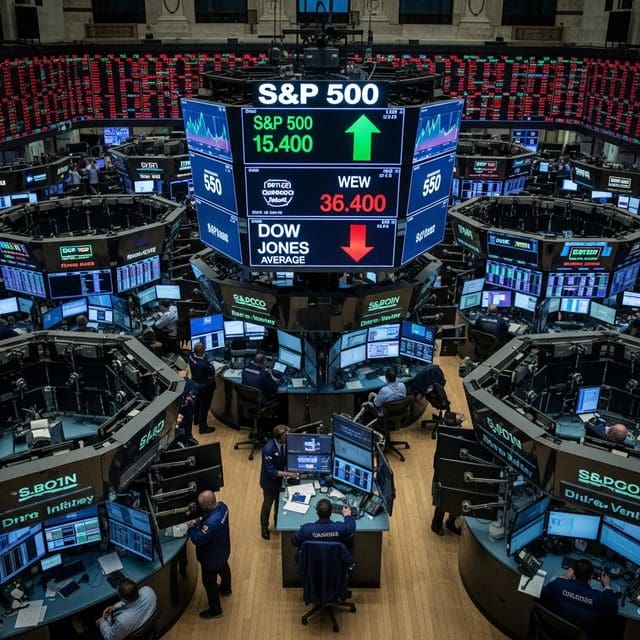
Major indices showed little conviction today as a semiconductor sell-off balanced gains in defensive sectors following a weaker-than-expected June jobs report.
Global financial markets exhibited a lack of clear direction during the latest session, with the S&P 500 (SPY) drifting down a marginal 0.11%. This muted performance masks a significant rotation under the surface of the American economy, as investors weigh cooling labor data against a sharp correction in the technology sector. While the Dow Jones Industrial Average surged more than 590 points to reach a record close of 52,900.07, the tech-heavy Nasdaq fell 0.8%, driven largely by a retreat in semiconductor shares. This divergence highlights a market in transition, where the high-flying AI narrative is being tested by the sobering realities of a slowing domestic labor market.
The primary catalyst for this divergence was the June nonfarm payrolls report, which showed the U.S. economy added only 57,000 jobs—well below the 113,000 anticipated by analysts. For the American taxpayer, this cooling labor market signals a shift in the Federal Reserve’s trajectory. Federal Reserve Chair Kevin Warsh noted that inflation risks have eased, a sentiment that provided a tailwind for gold prices and trimmed recent gains in the U.S. dollar. While slower job growth is a concern for Main Street, Wall Street interpreted the data as a sign that the central bank may finally move away from its hawkish stance, providing a boost to value-oriented and cyclical stocks that dominate the Dow.
The volatility in the chip sector, which saw significant sell-offs in names like AMD, Micron, and Intel, followed a sharp 7.9% plunge in South Korea’s Kospi index. This international spillover highlights the interconnected risks of the modern digital economy and the vulnerability of concentrated tech portfolios. As global equity markets edge lower, they appear set for a weekly decline, largely due to profit-taking in these previously dominant sectors. However, the Trump administration offered a potential bright spot for the domestic AI industry by lifting export controls on Anthropic’s Claude Fable 5 model on June 30, with full public access restored by July 1, signaling a shift in how the government manages high-tech trade and national sovereignty in the digital age.
In commodities, Brent crude futures fell 4.34%, providing some relief for household energy costs even as global equity markets struggled to find a footing. The currency markets also reacted to the shifting macro narrative, as the dollar’s earlier gains were pared back following Warsh’s commentary. For those looking beyond traditional equities, Vantage Markets launched a 24/7 gold CFD trading platform on July 4, allowing for continuous price discovery in a commodity that has become a favored hedge against the current monetary uncertainty.
Institutional activity remained steady despite the index-level stagnation, showing that industrial capital is still moving. Skanska announced a NOK 1.1 billion contract for an aluminum wire rod production facility in Norway and divested a Swedish multifamily project to Folksam Group for SEK 570 million. Additionally, the expansion of AEON Pay into Zambia through Airtel and MTN Mobile Money suggests that digital asset settlement continues to grow in emerging markets. Domestically, Ecopetrol Group confirmed receiving full payment for its FEPC account receivable balance via the Colombian Ministry of Finance, and OCI N.V. received a recommendation for an all-cash offer from NNS at EUR 4.10 per share.
For working households, the takeaway from today’s market action is one of transition and caution. The ‘hot streak’ of the labor market appears to be tempering, which may eventually lead to lower borrowing costs if the Federal Reserve responds to the cooling data. However, the persistent weakness in high-growth tech stocks suggests that the era of easy gains in the silicon sector may be facing a necessary market correction. As the SPY sits in a ‘muted but nervous’ tape, the focus remains on whether the broader economy can achieve a soft landing or if the invisible pressures of centralized financial control will continue to stifle Main Street’s growth.
Jordan Lee serves as the Senior Correspondent for Wall Street, Finance, and Monetary Systems at Just Right News. Based in the heart of the world’s financial capital, New York City, Lee brings a sharp, principled eye to the complex mechanisms that drive the global economy. His reporting is defined by a commitment to fiscal responsibility, the defense of the free market, and a deep-seated belief that a transparent monetary system is the bedrock of a free society.
Raised in Portland, Oregon, Lee’s perspective was forged in a city that has undergone significant cultural and economic shifts. His upbringing in the Pacific Northwest instilled in him a profound appreciation for the industriousness of small business owners and the importance of local economic stability. Watching the evolution of his hometown’s landscape sparked an early interest in how federal fiscal policy and large-scale financial trends eventually trickle down to the average citizen. This background provides him with a unique vantage point; he understands the growing disconnect between the policy-making elite and the reality of Main Street, a theme that frequently resonates throughout his work.
Now operating from his base in New York City, Lee bridges the gap between the high-stakes trading floors of Manhattan and the households of everyday Americans. He views the financial sector not merely as a collection of numbers and tickers, but as a vital engine of American prosperity that requires constant vigilance and accountability. His reporting often highlights the dangers of centralized financial control and the necessity of maintaining a system that rewards merit, risk-taking, and innovation.
As the creator and lead of the featured series, “The Invisible Economy,” Lee pulls back the curtain on the often-opaque world of monetary systems. He specializes in translating the dense jargon of central banking and international finance into actionable insights for the Just Right News audience. His work explores the “invisible” forces—such as inflationary pressures, regulatory creep, and the expansion of the administrative state—that erode the purchasing power of American families. By focusing on these systemic issues, Lee empowers readers to understand the hidden forces shaping their financial independence.
Lee’s journalistic philosophy is rooted in a steadfast commitment to traditional American values. As an Asian American professional who has navigated the competitive corridors of the financial world, he is a vocal advocate for meritocracy and the preservation of the American Dream. He believes that a stable currency and a predictable regulatory environment are essential for national sovereignty and individual liberty. His reporting frequently warns against the risks of government overreach in the private sector, arguing that the most effective solutions to economic challenges arise from competition and individual enterprise rather than bureaucratic mandates.
At Just Right News, Jordan Lee remains dedicated to providing a clear-eyed defense of the taxpayer. Whether he is analyzing market volatility or investigating the long-term implications of national debt, his mission is to provide the truth about where the money is going and what it means for the future of the country. Through his rigorous analysis and principled stance, Lee has become a trusted voice for those who value a strong, sovereign, and fiscally sound America.