
FTAI Infrastructure says a planned energy-logistics acquisition could more than double existing Adjusted EBITDA, but available materials disclose no merger challenge or market-power review.
FTAI Infrastructure’s planned acquisition of energy-logistics assets from USD Group could materially expand the company’s earnings base. But the available account of the deal offers little basis for judging its effect on competition—and reports no Federal Trade Commission or Justice Department investigation or challenge.
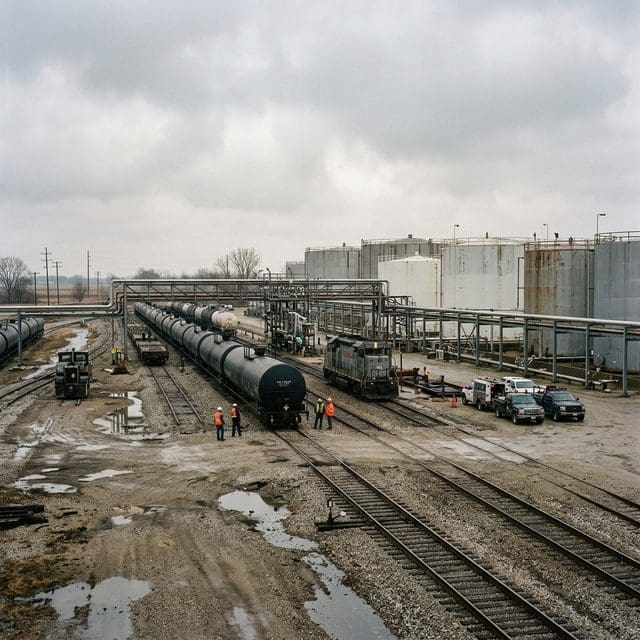
In a Motley Fool transcript of FTAI Infrastructure’s Nov. 5 earnings call, published Nov. 6, management said the USD assets generate approximately $50 million in annual EBITDA at contracted minimum volumes. The company expects that contribution to more than double its existing Adjusted EBITDA, according to the transcript. Those are management’s projections, not an independent assessment of the transaction’s competitive impact.
That is a significant growth claim. It is not, on its own, evidence that the deal will reduce competition, raise prices or harm customers. The available transcript and FTAI Infrastructure’s Nov. 5 release describe an energy-logistics acquisition but do not report a monopoly allegation, an antitrust remedy or a merger review by federal enforcers.
The distinction matters. Large transactions can reshape markets, but a headline about an acquisition—or a projection of substantial earnings growth—does not establish that a company is gaining monopoly power. Nor does the absence of a disclosed enforcement action establish that regulators have examined every competitive consequence. The materials available for this account simply do not provide evidence of an FTC or DOJ case.
They also leave important questions unanswered. The reported $50 million figure is tied to contracted minimum volumes; the transcript summary does not detail the contracts, identify affected customers or explain how many competing logistics providers serve the relevant markets. It does not say whether customers can readily switch providers, what alternatives they have, or whether the acquired assets serve markets where competition is already limited.
Those details are essential to a grounded assessment of market power. A transaction can expand a company’s operations without eliminating meaningful alternatives for customers. Conversely, a market with few practical alternatives can make even a seemingly narrow combination consequential for prices, service or bargaining power. The available material does not establish which conditions apply here.
For smaller businesses, the stakes of logistics competition can be practical: access to transportation and related infrastructure may affect operating costs and the ability to reach customers. But the sources provided do not identify small-business customers or document any effect on their costs. Any claim that the acquisition will either benefit or disadvantage them would go beyond the evidence available.
The same limits apply to the price and other terms of the acquisition. The cited transcript and release identify the transaction as a purchase of USD Group energy-logistics assets, but the supplied material does not provide a verified purchase price. It would be premature to infer the deal’s financing, valuation or competitive reach from the earnings projection alone. Nor does the reported expected contribution establish whether projected results will be realized.
For now, the verifiable story is narrower than an antitrust headline: FTAI Infrastructure is pursuing an acquisition that management expects to contribute approximately $50 million in annual EBITDA at contracted minimum volumes and more than double existing Adjusted EBITDA. No challenge or investigation is reported in the available sources.
That leaves regulators, investors and customers with a basic test for any further scrutiny: whether the transaction combines assets in a way that materially narrows alternatives or increases the company’s ability to dictate terms. The public information cited here does not answer that question. It does show why deal claims deserve close examination—and why financial growth should not be confused with proof of either consumer harm or competitive benefit.
Greg Sanders serves as the Senior Correspondent for Corporate Power and Antitrust at Just Right News, where he brings a principled, conservative perspective to the complex intersection of big business, government regulation, and the American consumer. With a career dedicated to investigative depth and economic clarity, Greg has become a leading voice in examining how the consolidation of industry power impacts the foundational values of the free market and individual liberty.
Raised in Denver, Colorado, Greg’s reporting is deeply informed by the Western spirit of independence and a healthy skepticism of centralized authority. Growing up in the shadows of the Rockies, he witnessed firsthand the importance of local entrepreneurship and the vital role that small-medium enterprises play in sustaining vibrant communities. This upbringing instilled in him a belief that the American Dream is best preserved when the playing field remains level and when competition—rather than backroom deals between corporate lobbyists and federal regulators—dictates success. For Greg, the rugged individualism of his home state serves as a constant reminder that the economy should serve the people, not the other way around.
Now based in Chicago, Illinois, Greg operates from the heart of the nation’s industrial and financial crossroads. His location in the Midwest provides him with a unique vantage point to observe the real-world consequences of corporate overreach. From the boardrooms of the Loop to the manufacturing hubs that define the region, he tracks the movement of capital and the shifting tides of market influence. Chicago’s history as a center of trade and labor offers a rich backdrop for his work, allowing him to bridge the gap between high-level economic theory and the lived experiences of hardworking Americans who feel the squeeze of monopolistic practices.
At Just Right News, Greg’s beat focuses on the “new monopolies” and the rise of “woke” corporate culture. He argues that when corporations become too large, they often abandon their fiduciary duties to shareholders in favor of social engineering and political posturing. His reporting seeks to hold these “Titans” accountable, ensuring that the power of the purse is not used to silence dissent or bypass the democratic process. He is a firm advocate for the idea that true conservatism requires a vigilant defense of competition, preventing any single entity—public or private—from exerting undue control over the lives of citizens.
This mission is most clearly seen in his acclaimed feature series, “The Titans and the Toll.” In this ongoing project, Greg explores the human cost of market consolidation, from the erosion of consumer choice to the decline of local economies. Through rigorous analysis and boots-on-the-ground reporting, he documents how the concentration of power in sectors like tech, agriculture, and finance creates a “toll” paid by the average family.
Greg Sanders remains committed to the idea that a transparent, competitive market is the greatest engine for prosperity ever devised. Through his work at Just Right News, he continues to provide the essential oversight necessary to protect that engine from the encroaching influence of corporate giants and the bureaucratic structures that enable them.