
Australian research finds the tax’s apparent burden shifts depending on whether it is compared with annual income, spending or longer-term household resources.
A new Australian study complicates the claim that consumption taxes always fall hardest on households with the lowest incomes. Its central finding is that the goods and services tax (GST) looks different depending on whether researchers compare it with annual income, spending or resources accumulated over time.
Reported by Phys.org on Oct. 15 and described by the University of New South Wales, the study used 2015–16 data from Australia’s Household, Income and Labour Dynamics in Australia survey, supplemented by several other survey years. Researchers compared GST with disposable income, spending, wealth and longer-term household resources.
Measured against income in a single year, GST remains regressive: lower-income households can pay a larger share of that year’s income in tax. But the researchers found the tax was broadly proportional to household spending. Averaging income over multiple years also narrowed the differences visible in a one-year comparison. Each measure answers a different question about who bears the cost; none makes the others irrelevant.
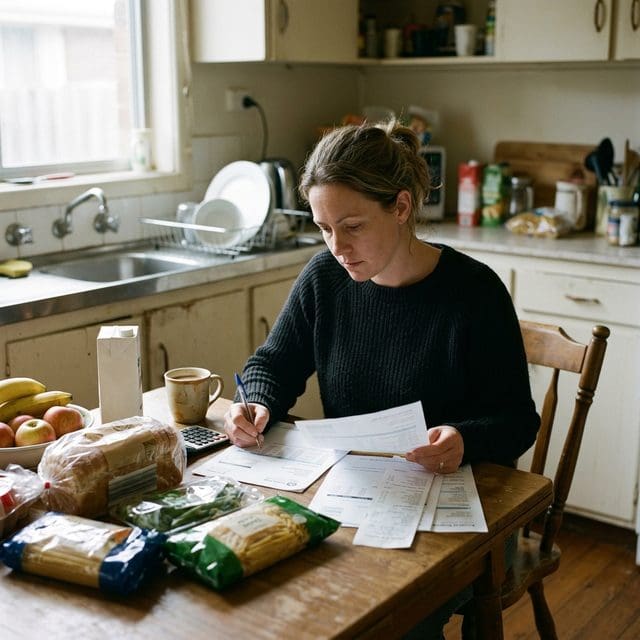
A household’s income in one year may not capture its underlying financial position. Researchers cited temporary shocks such as unemployment, study, parental leave and job changes. A household with low earnings in a given year may maintain its spending by drawing on savings or borrowing, or by relying on income earned in other years. Comparing tax with current income alone can therefore make the burden appear larger relative to a household’s resources than a longer view does.
The study also considers wealth and inheritance. Higher-income households tend to save more, UNSW reported, so some GST may be paid later when accumulated wealth is spent. Wealth passed to heirs may also be spent by a future generation. This raises a question that annual-income comparisons cannot settle: whether to assess the burden when income is earned, wealth accumulated or savings eventually used for purchases.
That broader accounting does not mean a tax paid at the checkout is painless. For households with little savings or sharply reduced earnings, it reduces money available for other needs. Annual-income measures can capture pressure on people facing unstable earnings, while spending and longer-term resources offer other views of the same distribution. The findings underscore the choice of measure; they do not establish that all households can absorb the tax equally.
The research concerns Australia, not U.S. sales taxes, SNAP, child poverty or American mobility. Its findings should not be treated as direct evidence about those subjects. Australia’s tax system and household circumstances are not a substitute for U.S. data.
The researchers’ policy implication is that increasing or broadening GST could be progressive if the additional revenue were returned through household payments or rebates. That is a possibility, not a guarantee: the study does not specify a U.S. rebate plan or establish what support would compensate any particular family. The design and delivery of assistance would matter, especially for households facing immediate expenses.
For policymakers, the broader lesson is to identify the yardstick before declaring a consumption tax fair or unfair. Annual income, spending and longer-term resources can tell different stories about who pays. The Australian findings do not prescribe U.S. policy, but they show why tax debates benefit from accounting for income volatility, savings and wealth—not just a single year’s paycheck.
James Foster serves as the Senior Correspondent for Inequality and the Social Safety Net at Just Right News, where he brings a principled and nuanced perspective to the most pressing economic challenges facing the nation. With a career dedicated to exploring the intersection of policy and personal responsibility, Foster has become a leading voice in documenting how government programs and economic shifts impact the American family. His reporting is characterized by a commitment to the “human element,” moving beyond cold statistics to highlight the stories of resilience, work, and community that define the modern American experience.
Foster’s perspective is deeply rooted in his upbringing in Birmingham, Alabama. Growing up in a city with a rich industrial heritage and a history of economic transformation, he witnessed firsthand the importance of the dignity of work and the strength of local institutions. In Birmingham, he saw how the most effective safety nets were often those woven by neighbors, faith-based organizations, and local civic groups. This background instilled in him a lifelong skepticism of “one-size-fits-all” solutions from distant bureaucracies, favoring instead the localized, community-driven support systems that he frequently champions in his writing.
Now based in Atlanta, Georgia, Foster operates from one of the most dynamic and rapidly evolving metropolitan hubs in the South. His location provides a front-row seat to the stark contrasts of the modern economy. From the gleaming towers of Atlanta’s financial districts to the struggling neighborhoods on the city’s periphery, Foster finds the stories that illustrate the complexities of upward mobility. His reporting from the Sun Belt serves as a microcosm for the national debate on poverty, highlighting how inflation, housing costs, and labor market shifts affect the working class in real-time.
As the lead for the acclaimed feature series “America’s Balancing Act,” Foster explores the delicate tension between providing a necessary hand up and fostering long-term independence. The series has become a cornerstone of Just Right News, offering a deep dive into the unintended consequences of social welfare policies. Foster’s work often focuses on the “cliff effect” and other systemic hurdles that can inadvertently discourage employment, arguing that true compassion is measured by how many people are empowered to leave the safety net, rather than how many are added to it.
Throughout his tenure, Foster has remained dedicated to the mission of Just Right News, providing a clear-eyed, conservative analysis of social issues. He believes that a free society thrives when individuals are empowered and the private sector is allowed to innovate. Whether he is interviewing small business owners about the challenges of a changing workforce or documenting the success of private charitable initiatives, Foster’s goal is to provide readers with the truth about the state of the American Dream. His work serves as a vital reminder that while the challenges of inequality are great, the solutions are often found in the strength of the American spirit and the preservation of traditional values.