
While the S&P 500 shows modest gains, rising Treasury yields and international fiscal instability signal a tightening economic environment for American taxpayers and global investors alike.
Financial markets displayed a deceptive calm on Friday as the SPY benchmark edged up 0.23%, masking a turbulent undercurrent in the global monetary system. While domestic indices like the S&P 500 and Nasdaq Composite showed marginal gains, the broader economic landscape remains defined by an aggressive rotation into the U.S. dollar and a deepening sell-off in sovereign debt. For the American household, these shifts represent more than just screen flickers; they signal a persistent era of high borrowing costs and inflationary pressure that threatens the foundation of fiscal responsibility.
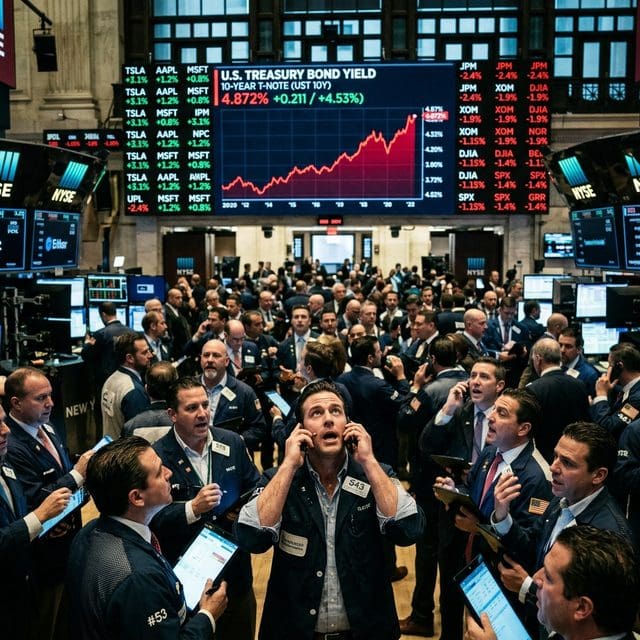
The U.S. 10-year Treasury yield recently touched 5.3445%, its highest level in nearly a quarter-century. Although yields eased slightly to 5.25%, the message to Main Street is clear: the era of cheap credit is over. This spike in government borrowing costs directly influences mortgage rates and consumer loans, effectively tightening the noose on discretionary spending. Markets are currently pricing a 76% probability that the Federal Reserve will maintain these elevated rates through October, a sharp increase from the 29% probability seen just a week ago. This shift suggests that the central bank remains myopically focused on price pressures, even as the burden on the taxpayer grows.
International markets reflect even greater instability, highlighting the fragility of centralized financial control. In Asia, the MSCI Asia-Pacific index fell 0.3%, headed for a 1.5% weekly loss, while Hong Kong’s Hang Seng dropped a staggering 2.6%. The contagion of fiscal concern has also reached Europe, where the spread between French and German 10-year bond yields widened to over 140 basis points, the highest point since 2012. Investors are increasingly skeptical of France’s ability to manage its €43 billion budget cut proposal as public debt approaches 120% of GDP, pushing the euro to its lowest level against the dollar since May 2025.
Energy costs continue to act as a hidden tax on the working class. While Brent crude slipped below $100 a barrel following reports of potential EU reserve releases, prices remain elevated due to Middle East tensions and export suspensions from China. These supply-side shocks, combined with a projected 3.2% year-over-year wage growth, keep the Federal Reserve in a defensive posture. A stronger-than-expected jobs report, with economists anticipating 90,000 new positions, could further embolden central bankers to prioritize inflation suppression over market liquidity, potentially reviving expectations for another rate hike.
In the private sector, the “Invisible Economy” continues to consolidate power through massive capital shifts. Akamai recently secured a $12 billion cloud computing deal with Anthropic, highlighting a pivot toward AI infrastructure that Bain & Co. projects could reach $6 trillion annually by 2031. Furthermore, OpenAI launched “dots,” an AI agent for high-end subscribers, intensifying the race for technological dominance. While these innovations represent free-market progress, they occur against a backdrop of corporate restructuring, such as Gunvor Group Ltd redomiciling to Singapore as Centalion Group Ltd and Paramount Skydance finalizing its merger with Warner Bros. Discovery.
As the September nonfarm payrolls report looms, the divergence between Wall Street’s modest daily gains and the structural rot in global debt markets grows. The stability of the American monetary system depends on a return to meritocracy and fiscal discipline that has yet to materialize. With the dollar index sitting at its highest level since April 2025, the global flight to safety suggests that the road ahead for the American taxpayer will be defined by navigating a landscape of high interest rates, eroding purchasing power, and the consequences of centralized economic overreach.
Jordan Lee serves as the Senior Correspondent for Wall Street, Finance, and Monetary Systems at Just Right News. Based in the heart of the world’s financial capital, New York City, Lee brings a sharp, principled eye to the complex mechanisms that drive the global economy. His reporting is defined by a commitment to fiscal responsibility, the defense of the free market, and a deep-seated belief that a transparent monetary system is the bedrock of a free society.
Raised in Portland, Oregon, Lee’s perspective was forged in a city that has undergone significant cultural and economic shifts. His upbringing in the Pacific Northwest instilled in him a profound appreciation for the industriousness of small business owners and the importance of local economic stability. Watching the evolution of his hometown’s landscape sparked an early interest in how federal fiscal policy and large-scale financial trends eventually trickle down to the average citizen. This background provides him with a unique vantage point; he understands the growing disconnect between the policy-making elite and the reality of Main Street, a theme that frequently resonates throughout his work.
Now operating from his base in New York City, Lee bridges the gap between the high-stakes trading floors of Manhattan and the households of everyday Americans. He views the financial sector not merely as a collection of numbers and tickers, but as a vital engine of American prosperity that requires constant vigilance and accountability. His reporting often highlights the dangers of centralized financial control and the necessity of maintaining a system that rewards merit, risk-taking, and innovation.
As the creator and lead of the featured series, “The Invisible Economy,” Lee pulls back the curtain on the often-opaque world of monetary systems. He specializes in translating the dense jargon of central banking and international finance into actionable insights for the Just Right News audience. His work explores the “invisible” forces—such as inflationary pressures, regulatory creep, and the expansion of the administrative state—that erode the purchasing power of American families. By focusing on these systemic issues, Lee empowers readers to understand the hidden forces shaping their financial independence.
Lee’s journalistic philosophy is rooted in a steadfast commitment to traditional American values. As an Asian American professional who has navigated the competitive corridors of the financial world, he is a vocal advocate for meritocracy and the preservation of the American Dream. He believes that a stable currency and a predictable regulatory environment are essential for national sovereignty and individual liberty. His reporting frequently warns against the risks of government overreach in the private sector, arguing that the most effective solutions to economic challenges arise from competition and individual enterprise rather than bureaucratic mandates.
At Just Right News, Jordan Lee remains dedicated to providing a clear-eyed defense of the taxpayer. Whether he is analyzing market volatility or investigating the long-term implications of national debt, his mission is to provide the truth about where the money is going and what it means for the future of the country. Through his rigorous analysis and principled stance, Lee has become a trusted voice for those who value a strong, sovereign, and fiscally sound America.