
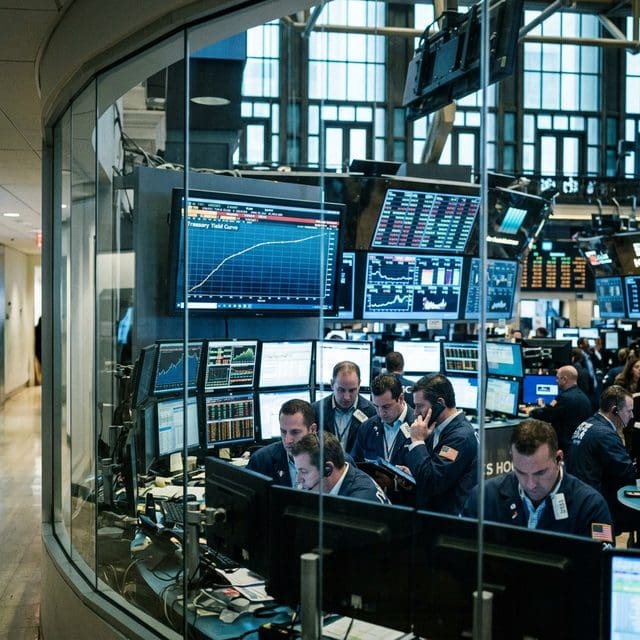
With SPY unchanged, markets still repriced risk beneath the surface as chip shares weakened, bond yields eased and investors weighed inflation, bank results and energy disruptions.
SPY was unchanged on the session, a calm headline for a market moving in several directions at once. Global equities were mixed and volatile: semiconductor and other technology shares faced pressure, while European stocks rose and government bonds drew renewed demand. For working households, that split matters more than a flat index alone: energy costs, borrowing rates and retirement portfolios can respond to different forces even when a broad U.S. benchmark goes nowhere.
CaixaBank Research’s October 14 market report said the STOXX 600 touched a one-week high as oil prices and bond yields eased. Asian equities, by contrast, reached a two-month low before recovering. The diverging performance reflects a market reassessing risk rather than moving in lockstep. The report linked weakness in global stocks to chipmakers and concerns over whether the scale of artificial-intelligence investment can be sustained.
That pressure was especially visible in parts of Asia. Anadolu Agency reported Micron fell 3.6% and SK Hynix lost 3.2% on October 14, while AMD and Western Digital also declined. The figures underscore how a handful of technology and semiconductor companies can weigh on major indices even as other sectors hold up. With SPY flat, investors should not mistake an unchanged benchmark for an absence of volatility within it.
Government bonds benefited as investors reduced equity exposure, according to CaixaBank Research. Yields eased, though the available market reports do not establish a single reliable closing figure for U.S. Treasury maturities. The direction matters to households: lower long-term yields can eventually ease some borrowing costs, including mortgages, but the effect is not immediate and depends on lenders and broader market conditions. Higher yields have already weighed on housing and auto demand, Fed Governor Christopher Waller said.
The next major test for rate expectations was September U.S. consumer-price data, due October 14. Economists surveyed by The Wall Street Journal expected annual inflation of 3.6%, up from 3.4% in August. LSEG put the probability of the Federal Reserve holding rates in October at 78% and the probability of a December hike at 88%. Those estimates are market pricing, not Fed commitments. New York Fed President John Williams said another hike could be appropriate this year, while seeing no need for one in 2027.
Energy remains a potential source of pressure for household budgets. CaixaBank reported December Brent crude ended lower, despite a continuing geopolitical risk premium, while European natural gas prices reached €85.90 per megawatt-hour, a four-year high. Low storage and Middle East supply disruptions raised concerns about winter liquefied-natural-gas availability. Separately, U.S. diesel prices remained above $6 per gallon on October 13 amid a global shortage, Axios reported. Lower crude on a particular day does not quickly erase high fuel costs already reaching drivers and businesses.
Bank earnings added another crosscurrent. JPMorgan’s profit and revenue fell short of expectations, and its shares dropped nearly 1%, Anadolu Agency reported. Goldman Sachs shares slipped 0.2%; Wells Fargo fell 3.1% despite reporting better-than-expected profit. The mixed response shows that strong results do not guarantee a rising share price when investors are focused on expectations and revenue details.
Currency moves can also affect household costs through imported goods and travel, but the available reporting does not establish a sufficiently consistent dollar-wide move to draw a firm conclusion. For now, the clearest takeaway is the contrast between an unchanged SPY reading and meaningful shifts beneath it: weaker chips, easing yields, uncertain inflation and costly energy risks. Those pressures—not the day’s flat benchmark—will help determine whether markets and household expenses find relief.
Jordan Lee serves as the Senior Correspondent for Wall Street, Finance, and Monetary Systems at Just Right News. Based in the heart of the world’s financial capital, New York City, Lee brings a sharp, principled eye to the complex mechanisms that drive the global economy. His reporting is defined by a commitment to fiscal responsibility, the defense of the free market, and a deep-seated belief that a transparent monetary system is the bedrock of a free society.
Raised in Portland, Oregon, Lee’s perspective was forged in a city that has undergone significant cultural and economic shifts. His upbringing in the Pacific Northwest instilled in him a profound appreciation for the industriousness of small business owners and the importance of local economic stability. Watching the evolution of his hometown’s landscape sparked an early interest in how federal fiscal policy and large-scale financial trends eventually trickle down to the average citizen. This background provides him with a unique vantage point; he understands the growing disconnect between the policy-making elite and the reality of Main Street, a theme that frequently resonates throughout his work.
Now operating from his base in New York City, Lee bridges the gap between the high-stakes trading floors of Manhattan and the households of everyday Americans. He views the financial sector not merely as a collection of numbers and tickers, but as a vital engine of American prosperity that requires constant vigilance and accountability. His reporting often highlights the dangers of centralized financial control and the necessity of maintaining a system that rewards merit, risk-taking, and innovation.
As the creator and lead of the featured series, “The Invisible Economy,” Lee pulls back the curtain on the often-opaque world of monetary systems. He specializes in translating the dense jargon of central banking and international finance into actionable insights for the Just Right News audience. His work explores the “invisible” forces—such as inflationary pressures, regulatory creep, and the expansion of the administrative state—that erode the purchasing power of American families. By focusing on these systemic issues, Lee empowers readers to understand the hidden forces shaping their financial independence.
Lee’s journalistic philosophy is rooted in a steadfast commitment to traditional American values. As an Asian American professional who has navigated the competitive corridors of the financial world, he is a vocal advocate for meritocracy and the preservation of the American Dream. He believes that a stable currency and a predictable regulatory environment are essential for national sovereignty and individual liberty. His reporting frequently warns against the risks of government overreach in the private sector, arguing that the most effective solutions to economic challenges arise from competition and individual enterprise rather than bureaucratic mandates.
At Just Right News, Jordan Lee remains dedicated to providing a clear-eyed defense of the taxpayer. Whether he is analyzing market volatility or investigating the long-term implications of national debt, his mission is to provide the truth about where the money is going and what it means for the future of the country. Through his rigorous analysis and principled stance, Lee has become a trusted voice for those who value a strong, sovereign, and fiscally sound America.